
RBSE Class 12th 2017 -SS-30-2017 Previous Year Papers
Class 12th students hunting authentic previous year papers for -SS-30-2017 (2017) land here for a reason: the paper below matches how RBSE assessments are remembered from that year. RBSE Solution does not mix years on one page; each combination gets its own notes.
Skim the overview sections, then work through the scanned pages. Pair this practice with RBSE books and solutions when you need to relearn a concept a question exposed.
Paper details
Quick reference for this previous year papers page — confirm board, class, and year & subject before you study.
| Board | RBSE |
|---|---|
| Class | Class 12th |
| Exam year | 2017 |
| Subject | -SS-30-2017 |
| Resource type | Previous Year Papers |
| Category | RBSE Previous Year Question Papers |
| Website | RBSE Solution |
The table summarises this Previous Year Papers resource. Confirm RBSE, Class 12th, year 2017, and subject -SS-30-2017 before studying.
RBSE Solution organises previous year papers so each URL carries chapter-specific guidance — better for students and for search engines than one generic paragraph for the whole class.
How to practise with this question paper
Stage one: read the -SS-30-2017 question paper from 2017 without a timer and highlight command words — explain, prove, calculate, discuss. Stage two: attempt selected questions closed-book. Stage three: compare with solutions or teacher feedback.
Previous Year Papers work best when you log mistakes by topic, not only by question number. That log becomes your revision index before pre-boards.
Stay Connected with RBSE Solutions
Get exam updates, new PDFs, and important notices on the channels students already use.
RBSE Class 12th 2017 -SS-30-2017
Scroll through the Previous Year Papers pages for -SS-30-2017 (2017).





Rajasthan Board Class 12th -SS-30-2017 2017 solved Previous Year Question Papers
लेखाशास्त्र / ACCOUNTANCY
समय : 3¼ घण्टे | पूर्णांक : 80
SLNo. : नामांक / Roll No.
No. of Questions - 30 | No. of Printed Pages - 5
SS-30-Accountancy (Supp.)
उच्च माध्यमिक पूरक परीक्षा, 2017
SENIOR SECONDARY SUPPLEMENTARY EXAMINATION, 2017
परीक्षार्थियों के लिए सामान्य निर्देश :
GENERAL INSTRUCTIONS TO THE EXAMINEES :
-
परीक्षार्थी सर्वप्रथम अपने प्रश्न पत्र पर नामांक अनिवार्यत: लिखें।
Candidate must write first his / her Roll No. on the question paper compulsorily. -
सभी प्रश्न अनिवार्य हैं।
All the questions are compulsory. -
प्रत्येक प्रश्न का उत्तर दी गई उत्तर-पुस्तिका में ही लिखें।
Write the answer to each question in the given answer-book only. -
जिन प्रश्नों में आन्तरिक खण्ड हैं, उन सभी के उत्तर एक साथ ही लिखें।
For questions having more than one part, the answers to those parts are to be written together in continuity. -
प्रश्न पत्र के हिन्दी व अंग्रेजी रुपान्तर में किसी प्रकार की त्रुटि / अन्तर / विरोधाभास होने पर हिन्दी भाषा के प्रश्न को ही सही मानें।
If there is any error/difference/contradiction in Hindi & English versions of the question paper, the question of Hindi version should be treated valid.
SS-30-Accountancy [Turn Over
TEAR HERE TO OPEN THE QUESTION PAPER
प्रश्न पत्र को खोलने के लिए यहाँ से काटिए
निर्देश / Instructions
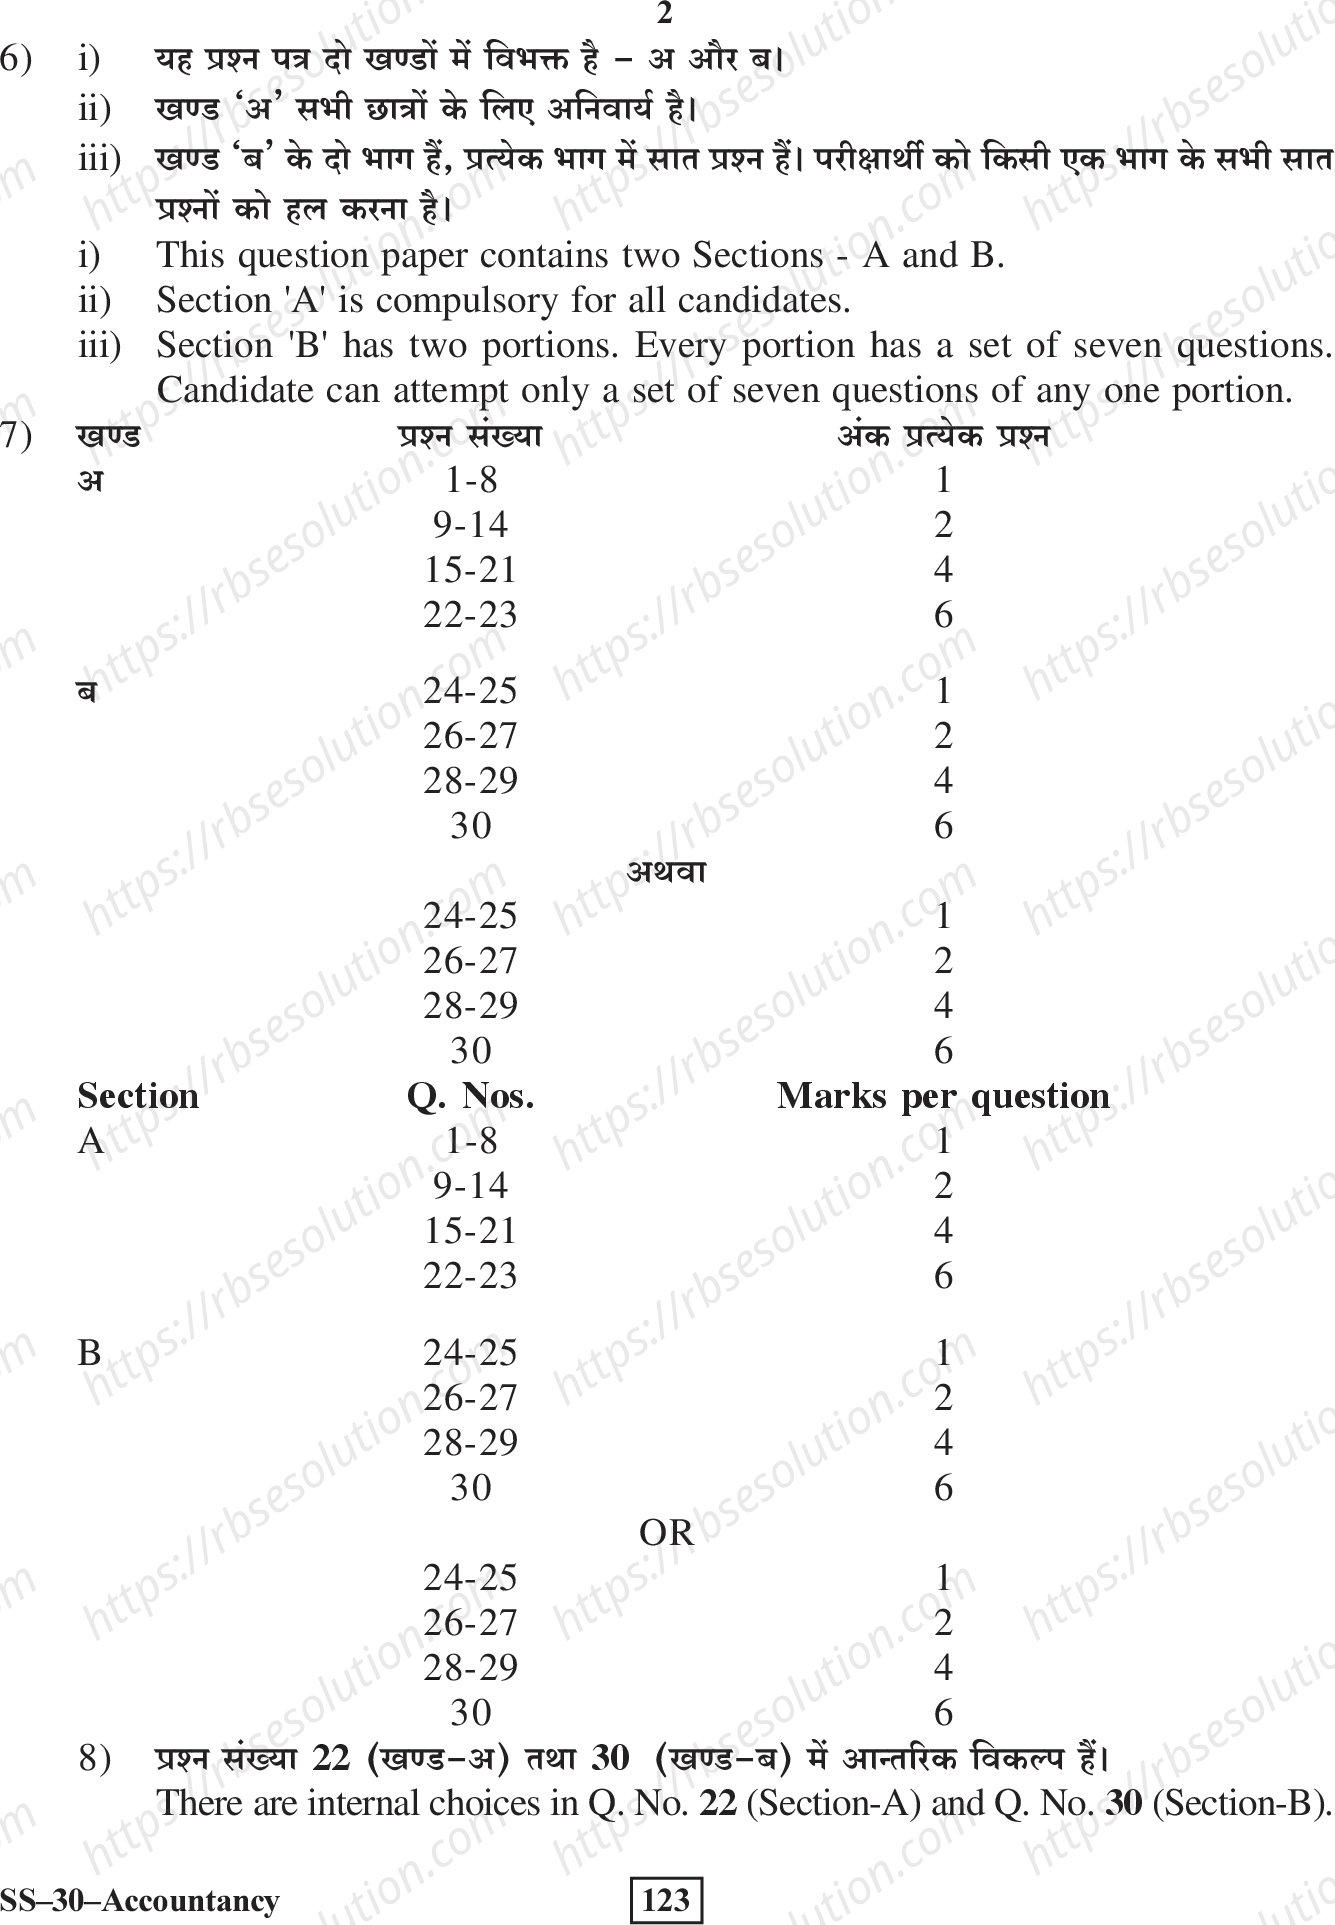
- यह प्रश्न पत्र दो खण्डों में विभक्त है - अ और ब।
- खण्ड 'अ' सभी छात्रों के लिए अनिवार्य है।
- खण्ड 'ब' के दो भाग हैं, प्रत्येक भाग में सात प्रश्न हैं। परीक्षार्थी को किसी एक भाग के सभी सात प्रश्नों को हल करना है।
- This question paper contains two Sections - A and B.
- Section 'A' is compulsory for all candidates.
- Section 'B' has two portions. Every portion has a set of seven questions. Candidate can attempt only a set of seven questions of any one portion.
अंक वितरण / Marks Distribution
| खण्ड / Section | प्रश्न संख्या / Q. Nos. | प्रति प्रश्न अंक / Marks per question |
|---|---|---|
| अ / A | 1-8 | 1 |
| 9-14 | 2 | |
| 15-21 | 3 | |
| 22-23 | 4 | |
| ब / B | 24-25 | 4 |
| 26-27 | 6 | |
| 28-29 | 8 | |
| 30 | 10 |
खण्ड ब के लिए वैकल्पिक प्रश्न / Alternative for Section B:
| प्रश्न संख्या / Q. Nos. | अंक / Marks |
|---|---|
| 24-25 | 4 |
| 26-27 | 6 |
| 28-29 | 8 |
| 30 | 10 |
आन्तरिक विकल्प / Internal Choices: प्रश्न संख्या 22 (खण्ड-अ) तथा 30 (खण्ड-ब) में आन्तरिक विकल्प हैं।
There are internal choices in Q. No. 22 (Section-A) and Q. No. 30 (Section-B).
SS-30—Accountancy 23
खण्ड - अ / SECTION - A
-
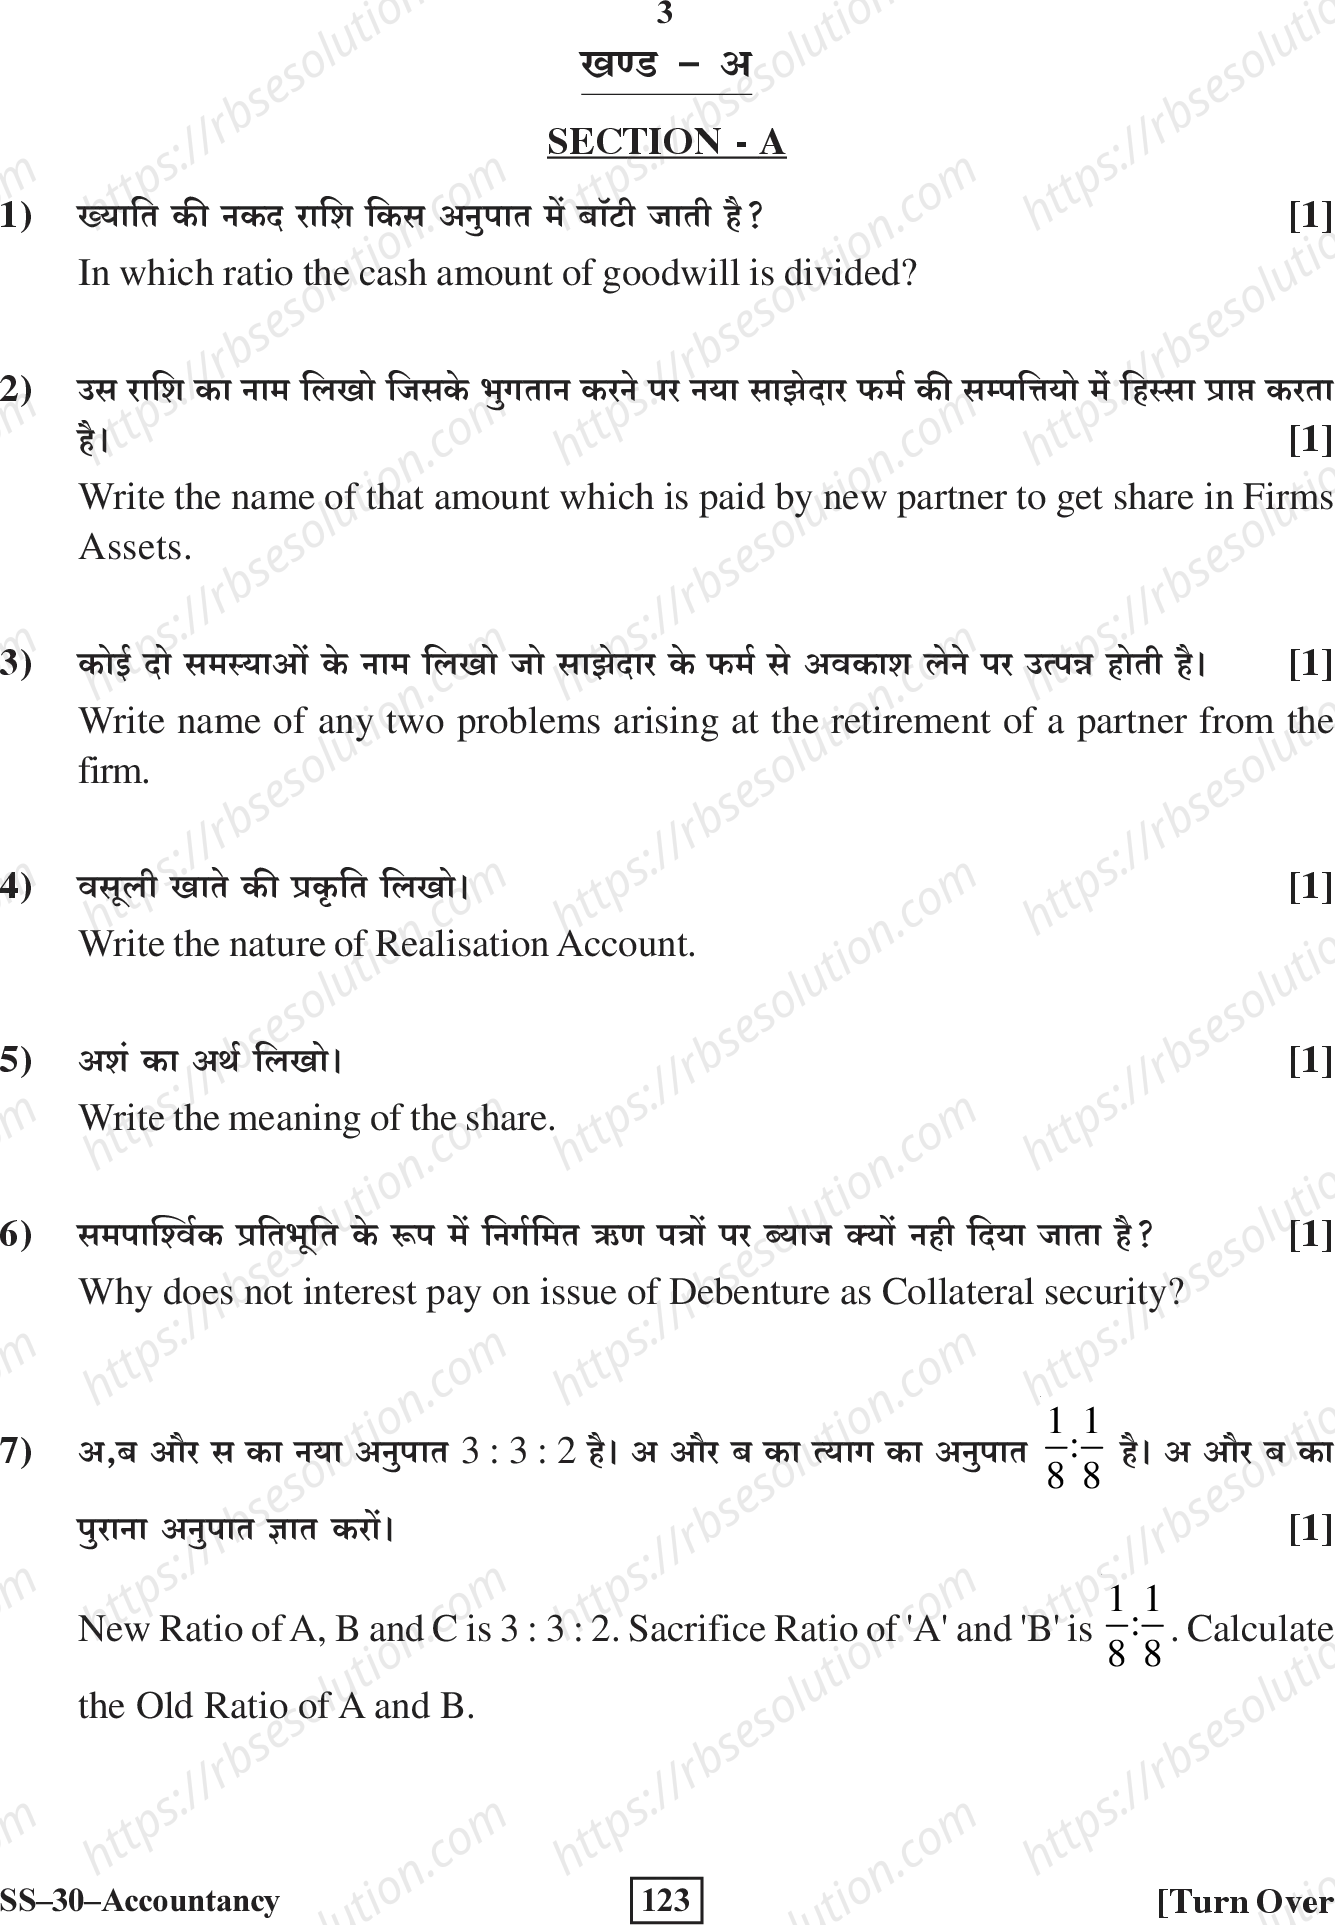
ख्याति की नकद राशि किस अनुपात में बाँटी जाती है?
In which ratio the cash amount of goodwill is divided?ख्याति की नकद राशि को पुराने साझेदारों के बीच उनके त्याग अनुपात (Sacrifice Ratio) में बाँटा जाता है।
-
उस राशि का नाम लिखो जिसके भुगतान करने पर नया साझेदार फर्म की सम्पत्तियों में हिस्सा प्राप्त करता है।
Write the name of that amount which is paid by new partner to get share in Firm's Assets.इस राशि को ख्याति (Goodwill) कहा जाता है।
-
कोई दो समस्याओं के नाम लिखो जो साझेदार के फर्म से अवकाश लेने पर उत्पन्न होती है।
Write name of any two problems arising at the retirement of a partner from the firm.- ख्याति का मूल्यांकन एवं उसका भुगतान।
- अवकाश लेने वाले साझेदार के पूँजी खाते का निपटान।
-
वसूली खाते की प्रकृति लिखो।
Write the nature of Realisation Account.वसूली खाता एक अस्थायी (Temporary) या नाममात्र (Nominal) खाता है, जो फर्म के विघटन के समय सम्पत्तियों की बिक्री और दायित्वों के भुगतान को दर्शाने के लिए बनाया जाता है।
-
अंश का अर्थ लिखो।
Write the meaning of the share.अंश (Share) किसी कम्पनी की पूँजी की एक छोटी इकाई है, जो कम्पनी में स्वामित्व को दर्शाती है। अंशधारक को लाभांश प्राप्त करने और कम्पनी के प्रबंधन में मतदान का अधिकार होता है।
-
समपार्श्विक प्रतिभूति के रूप में निर्गमित ऋण पत्रों पर ब्याज क्यों नहीं दिया जाता है?
Why does not interest pay on issue of Debenture as Collateral security?समपार्श्विक प्रतिभूति के रूप में निर्गमित ऋण पत्रों पर ब्याज नहीं दिया जाता है क्योंकि ये ऋण पत्र केवल गारंटी (Security) के रूप में जारी किए जाते हैं, न कि ऋण के रूप में। जब तक मूल ऋण चुकाया नहीं जाता, तब तक इन ऋण पत्रों को भुनाया नहीं जाता और न ही इन पर ब्याज दिया जाता है।
-
अ, ब और स का नया अनुपात 3:3:2 है। अ और ब का त्याग का अनुपात 8:8 है। अ और ब का पुराना अनुपात ज्ञात करो।
New Ratio of A, B and C is 3:3:2. Sacrifice Ratio of 'A' and 'B' is 8:8. Calculate the Old Ratio of A and B.हल:
नया अनुपात (New Ratio) = A : B : C = 3 : 3 : 2
त्याग अनुपात (Sacrifice Ratio) = A : B = 8 : 8 = 1 : 1माना कि पुराना अनुपात (Old Ratio) = A : B = x : y
त्याग अनुपात = पुराना अनुपात - नया अनुपात
A का त्याग = x - 3/8
B का त्याग = y - 3/8चूँकि त्याग अनुपात 1:1 है, इसलिए:
x - 3/8 = y - 3/8
⇒ x = yअतः पुराना अनुपात A : B = 1 : 1
उत्तर: अ और ब का पुराना अनुपात 1:1 है।
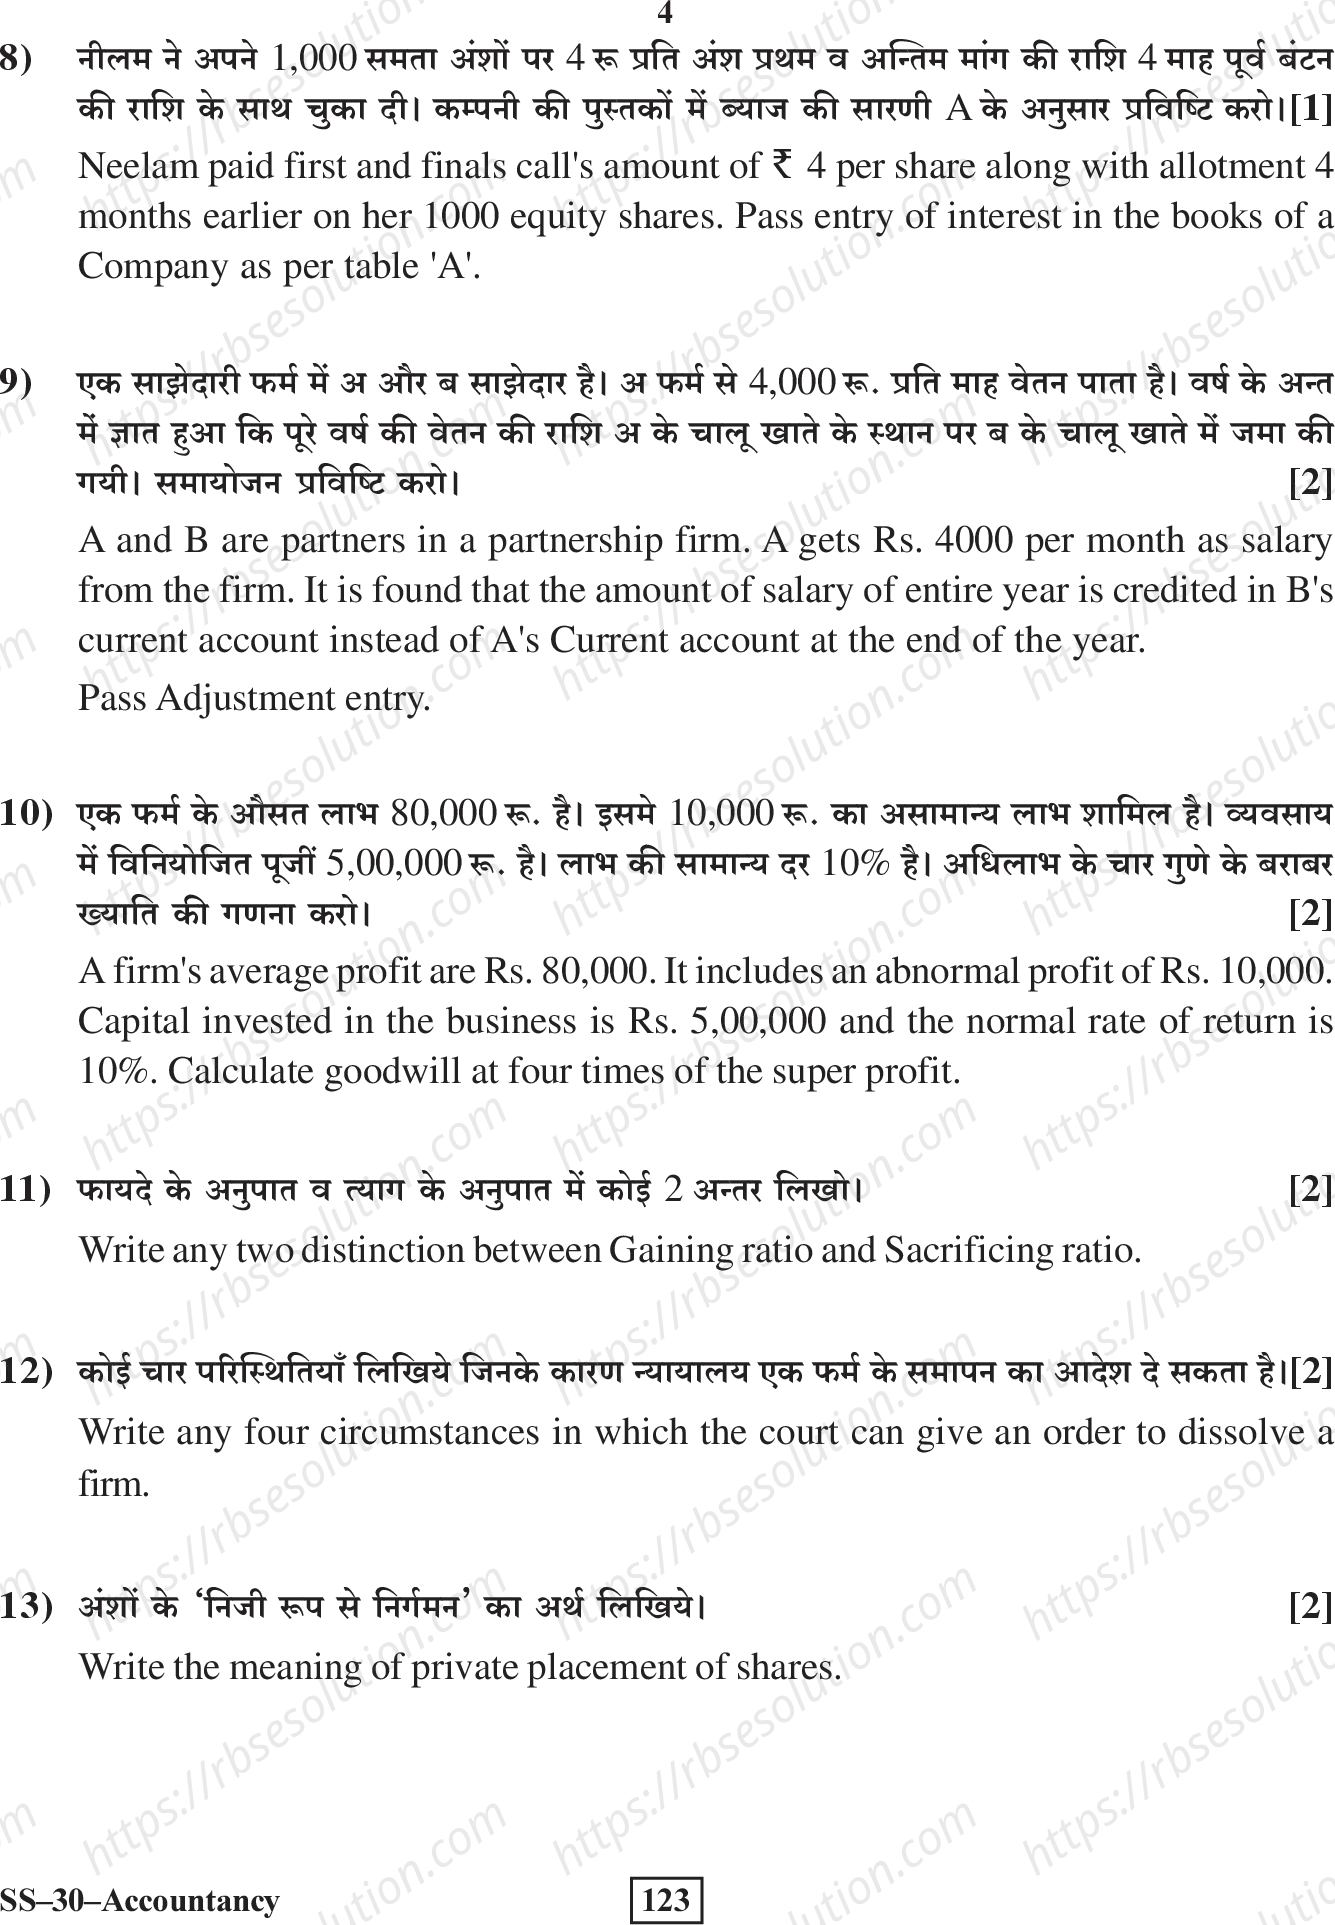
8. नीलम ने अपने 1,000 समता अंशों पर 4 रु प्रति अंश प्रथम व अन्तिम मांग की राशि 4 माह पूर्व बंटन की राशि के साथ चुका दी। कम्पनी की पुस्तकों में ब्याज की सारणी / के अनुसार प्रविष्टि कीजिए।
Neelam paid first and final call's amount of Rs. 4 per share along with allotment 4 months earlier on her 1,000 equity shares. Pass entry of interest in the books of a Company as per table 'A'.
हल:
प्रथम एवं अन्तिम मांग की राशि = 1,000 अंश × 4 रु = 4,000 रु
यह राशि 4 माह पूर्व चुकाई गई, अतः कम्पनी को ब्याज देना होगा।
ब्याज की गणना: माना ब्याज की दर 12% वार्षिक है (जैसा कि सारणी A में उल्लिखित है)।
ब्याज = 4,000 रु × 12/100 × 4/12 = 160 रु
प्रविष्टि:
| विवरण | नाम (Dr.) | जमा (Cr.) |
|---|---|---|
| ब्याज खाता नाम | 160 | |
| नीलम के खाते से | 160 | |
| (4 माह पूर्व भुगतान पर ब्याज) | ||
9. एक साझेदारी फर्म में अ और ब साझेदार है। अ फर्म से 4,000 रु प्रति माह वेतन पाता है। वर्ष के अन्त में ज्ञात हुआ कि पूरे वर्ष की वेतन की राशि अ के चालू खाते के स्थान पर ब के चालू खाते में जमा की गयी। समायोजन प्रविष्टि करो।
A and B are partners in a partnership firm. A gets Rs. 4000 per month as salary from the firm. It is found that the amount of salary of entire year is credited in B's current account instead of A's Current account at the end of the year. Pass Adjustment entry.
हल:
वर्ष भर का वेतन = 4,000 रु × 12 = 48,000 रु
यह राशि गलती से ब के खाते में जमा कर दी गई, जबकि अ को मिलनी चाहिए थी। अतः समायोजन प्रविष्टि:
| विवरण | नाम (Dr.) | जमा (Cr.) |
|---|---|---|
| ब का चालू खाता नाम | 48,000 | |
| अ के चालू खाते से | 48,000 | |
| (गलत जमा राशि का समायोजन) | ||
10. एक फर्म के औसत लाभ 80,000 रु है। इसमें 10,000 रु का असामान्य लाभ शामिल है। व्यवसाय में विनियोजित पूंजी 5,00,000 रु है। लाभ की सामान्य दर 10% है। अधिलाभ के चार गुणे के बराबर ख्याति की गणना करो।
A firm's average profit are Rs. 80,000. It includes an abnormal profit of Rs. 10,000. Capital invested in the business is Rs. 5,00,000 and the normal rate of return is 10%. Calculate goodwill at four times of the super profit.
हल:
सामान्य लाभ = औसत लाभ - असामान्य लाभ = 80,000 - 10,000 = 70,000 रु
सामान्य प्रतिफल = विनियोजित पूंजी × सामान्य दर = 5,00,000 × 10/100 = 50,000 रु
अधिलाभ = सामान्य लाभ - सामान्य प्रतिफल = 70,000 - 50,000 = 20,000 रु
ख्याति = अधिलाभ × 4 = 20,000 × 4 = 80,000 रु
11. फायदे के अनुपात व त्याग के अनुपात में कोई 2 अन्तर लिखो।
Write any two distinction between Gaining ratio and Sacrificing ratio.
| क्र. | त्याग का अनुपात (Sacrificing Ratio) | लाभ का अनुपात (Gaining Ratio) |
|---|---|---|
| 1. | यह उस अनुपात को दर्शाता है जिसमें पुराने साझेदार नए साझेदार के प्रवेश पर अपने लाभ का हिस्सा छोड़ते हैं। | यह उस अनुपात को दर्शाता है जिसमें शेष साझेदार किसी साझेदार के सेवानिवृत्त होने या मृत्यु पर उसका लाभ हिस्सा प्राप्त करते हैं। |
| 2. | इसकी गणना नए साझेदार के प्रवेश के समय की जाती है। | इसकी गणना साझेदार के सेवानिवृत्ति या मृत्यु के समय की जाती है। |
12. कोई चार परिस्थितियाँ लिखिये जिनके कारण न्यायालय एक फर्म के समापन का आदेश दे सकता है।
Write any four circumstances in which the court can give an order to dissolve a firm.
- जब कोई साझेदार मानसिक रूप से अक्षम हो जाए।
- जब कोई साझेदार स्थायी रूप से अपने कर्तव्यों का पालन करने में असमर्थ हो।
- जब फर्म का व्यवसाय केवल हानि पर चल रहा हो।
- जब न्यायालय को यह उचित लगे कि फर्म का विघटन न्यायसंगत और उचित है।
13. अंशों के "निजी रूप से निर्गमन" का अर्थ लिखिये।
Write the meaning of private placement of shares.
अर्थ: अंशों का निजी रूप से निर्गमन (Private Placement) एक ऐसी प्रक्रिया है जिसमें कंपनी अपने अंशों को सामान्य जनता को आमंत्रित किए बिना, केवल चुनिंदा निवेशकों (जैसे संस्थागत निवेशकों, म्यूचुअल फंडों, या बड़े निवेशकों) को बेचती है। इसमें प्रॉस्पेक्टस जारी नहीं किया जाता, बल्कि एक निजी निर्गमन दस्तावेज तैयार किया जाता है।
4) सम फीस ने 00 रू. वाले 2,000-9% ऋण पत्रों का सममूल्य पर निर्गमन किया जिनका शोधन 4% प्रीमीयम पर किया जाना है। इन्द्राज लिमिटेड की पुस्तकों में आवश्यक प्रविष्टियाँ कीजिये। [2]
Indraj limited issued 2000-9% debenture at the rate of Rs. 100 each at par which would be redeemed at 4% premium. Pass necessary entries in the books of the Indraj Limited.
Solution:
Journal Entries in the books of Indraj Limited
| Date | Particulars | L.F. | Debit (Rs.) | Credit (Rs.) |
|---|---|---|---|---|
| Bank A/c Dr. | 2,00,000 | |||
| To 9% Debentures A/c | 2,00,000 | |||
| (Being 2,000, 9% debentures of Rs. 100 each issued at par) | ||||
| 9% Debentures A/c Dr. | 2,00,000 | |||
| Loss on Issue of Debentures A/c Dr. | 8,000 | |||
| To Debentureholders A/c | 2,08,000 | |||
| (Being amount due to debentureholders on redemption at 4% premium) |
Working Note: Premium on redemption = 2,000 × 100 × 4% = Rs. 8,000.
5) साझेदारी संलेख के अभाव में लागू होने वाले कोई चार प्रावधान लिखिये। [4]
Write any four provisions applicable in the absence of partnership agreement.
Solution: In the absence of a partnership deed, the following provisions of the Indian Partnership Act, 1932 apply:
- Profit Sharing Ratio: Profits and losses are shared equally among all partners.
- Interest on Capital: No interest is allowed on partners' capital.
- Interest on Drawings: No interest is charged on partners' drawings.
- Remuneration: No partner is entitled to any salary or commission for their work in the firm.
6) मोहन और सोहन एक फर्म में साझेदार है। 31 मार्च 2016 को उनके पूंजी खाते क्रमश: 1,50,000 रू. एवं 1,60,000 रू. का शेष प्रकट करते हैं। वर्ष का लाभ 1,00,000 रू. बाँटा जा चूका है। अन्तिम खाते बनाते समय निम्न मदों का ध्यान नही रखा गया-
1. पूंजी पर 10% वार्षिक ब्याज प्राप्त करने के अधिकारी है।
2. वर्ष के दौरान मोहन और सोहन ने क्रमशः 20,000 रू. एवं 5,000 रू. का आहरण किया। आहरण पर 8% वार्षिक दर से 6 माह का ब्याज लगाना था।
भूल सुधार के लिए चालू वर्ष के अन्त में आवश्यक जर्नल प्रविष्टियाँ कीजिये। [4]
Mohan and Sohan are partners in a firm. As on 31st March 2016 their capital accounts balance showed Rs. 1,50,000 and Rs. 1,60,000 respectively. Profit of the year Rs. 1,00,000 have been distributed. The following items have been left out while preparing the final account.
1. The partners are entitled for interest on capital at the rate 10% per annum.
2. During the year Mohan and Sohan withdraw Rs. 20,000 and Rs. 5,000 respectively. Interest on Drawings was also to be charged at the rate 8% per annum for six months.
Pass necessary Journal entries for rectification of error at the end of the current year.
Solution:
Step 1: Calculate the omitted items
- Interest on Mohan's Capital = 1,50,000 × 10% = Rs. 15,000
- Interest on Sohan's Capital = 1,60,000 × 10% = Rs. 16,000
- Interest on Mohan's Drawings = 20,000 × 8% × 6/12 = Rs. 800
- Interest on Sohan's Drawings = 5,000 × 8% × 6/12 = Rs. 200
Step 2: Determine the net effect on profit
Total interest on capital (expense) = 15,000 + 16,000 = Rs. 31,000
Total interest on drawings (income) = 800 + 200 = Rs. 1,000
Net additional expense = 31,000 - 1,000 = Rs. 30,000
This reduces the profit by Rs. 30,000. Since profit was already distributed equally (Rs. 50,000 each), the adjustment is needed.
Step 3: Journal Entries for Rectification
| Date | Particulars | L.F. | Debit (Rs.) | Credit (Rs.) |
|---|---|---|---|---|
| Mohan's Capital A/c Dr. | 15,000 | |||
| Sohan's Capital A/c Dr. | 16,000 | |||
| To Interest on Capital A/c | 31,000 | |||
| (Being interest on capital credited to partners) | ||||
| Interest on Drawings A/c Dr. | 1,000 | |||
| To Mohan's Capital A/c | 800 | |||
| To Sohan's Capital A/c | 200 | |||
| (Being interest on drawings charged to partners) | ||||
| Profit & Loss Adjustment A/c Dr. | 30,000 | |||
| To Mohan's Capital A/c | 15,000 | |||
| To Sohan's Capital A/c | 15,000 | |||
| (Being the net adjustment of Rs. 30,000 (excess profit distributed) transferred to partners' capital accounts in equal ratio) |